Volkswagen approves historic 50,000 job cuts in bid to stabilise European auto sector
The German carmaker’s supervisory board has endorsed a sweeping restructuring plan designed to mitigate the impact of US tariffs and Chinese competition, while curbing the influence of the state of Lower Saxony.
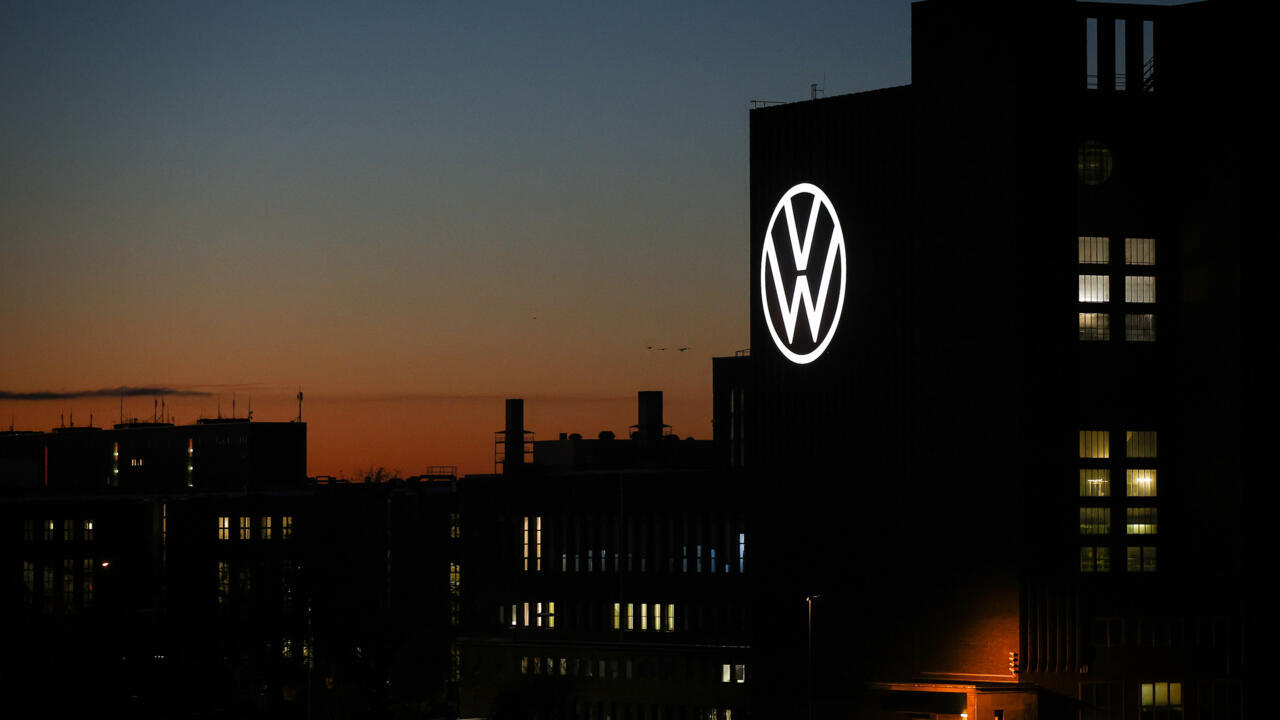
Volkswagen has secured approval for its most extensive restructuring in 89 years, with the supervisory board endorsing a plan to cut a further 50,000 jobs worldwide. The decision marks a significant shift in governance for Europe’s largest automaker, driven by the need to counter aggressive US import tariffs, global overcapacity, and intensifying competition from Chinese rivals.
The new workforce reduction is in addition to a previous cut of 50,000 positions already under way. While the company has not provided specific details on the timing of the reductions or how they will be distributed across its various brands and regions, the move is framed as a necessary adjustment to global workforce capacity.
A key component of the agreement involves exploring alternatives for four German plants that are expected to run out of production models within the next decade. This strategic review aims to address long-term industrial viability in a market where the group’s former primary revenue source, the Chinese market, has weakened considerably.
The deal also simplifies Volkswagen’s conglomerate structure, specifically limiting the influence of the supervisory board. Unions and the state of Lower Saxony, which hold a majority on the board, will have reduced sway over key decisions. This structural change effectively shelves the scenario of an extraordinary general meeting, a measure previously considered by management to push through plans against the interests of workers and the state.
Following weeks of tense negotiations between the board, majority owner Porsche SE, unions, and Lower Saxony, the agreement averts what sources described as a potential major clash. The idea of spinning off Volkswagen’s passenger car and components businesses is no longer being mentioned, suggesting a consolidation of the group’s core operations.
CEO Oliver Blume characterised the move as a "strong signal for the future," stating the company is taking responsibility for its workforce and industrial jobs worldwide. Union representatives described the situation as a "ceasefire," indicating that while a certain calm is returning, the relationship is far from permanently resolved.
Volkswagen shares, listed in Frankfurt, closed 7.9 per cent higher following the announcement, reflecting market relief over the avoidance of an unprecedented crisis at the German giant.