Digital Wallets: Security Benefits and Operational Limits for Consumers
While tokenisation and biometric authentication offer robust protection, reliance on device power and variable retail acceptance necessitates maintaining physical payment backups.
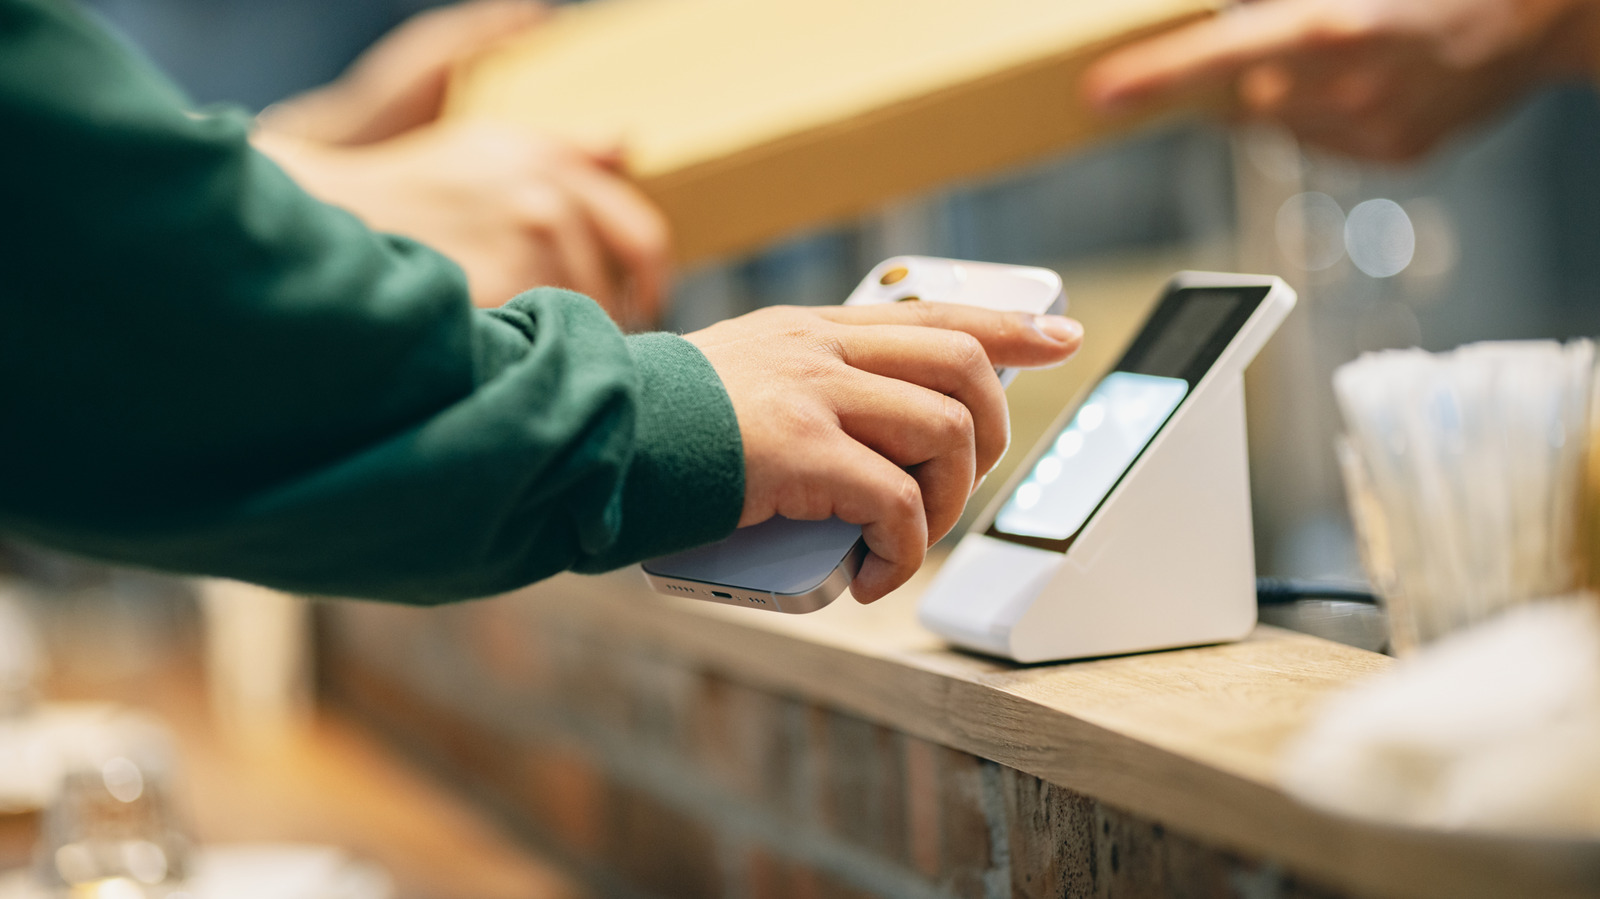
Digital wallets have evolved from niche offerings to widely accepted payment methods over the last decade, with platforms such as Apple Pay and Google Wallet now participating in nearly every major card network. The choice of wallet is typically dictated by device ecosystem, with Apple Pay serving iOS users, Google Wallet for Android, and Samsung Pay offering integration for Samsung devices, albeit with lower compatibility than its competitors. This consolidation allows users to store multiple credit and debit cards, loyalty programmes, and even digital IDs in certain jurisdictions, reducing the need to carry physical cards.
The primary advantage of these systems lies in enhanced security through tokenisation and biometric authentication. Unlike magnetic stripe swiping, which exposes raw card data, digital wallets generate a unique, one-time transaction ID for each purchase. This process, combined with device-specific PINs or facial recognition, significantly mitigates the risks associated with physical card skimming or unauthorised small-value transactions that often require no authentication. Furthermore, centralising payment details reduces the attack surface compared to storing card information across multiple shopping websites.
Convenience is another driver for adoption, with contactless payments processing near-instantly compared to chip readers. Users can manage various digital assets, including concert tickets, boarding passes, and hotel keys, within a single interface. For online transactions, digital wallets enable one-step checkout on participating apps and websites, eliminating the need to re-enter card details and reducing the potential for data entry errors. Smartwatches also extend this functionality, allowing payments from the wrist without retrieving a phone.
Despite these benefits, limitations remain. Digital payments are not universally accepted, and some retailers lack the necessary NFC scanners for contactless transactions. Reliance on device battery life presents a critical operational risk; if a phone powers down, users cannot make payments unless they have a backup physical method. Apple Pay’s Express Mode offers a partial solution, allowing transit and car key access for up to five hours after a low-battery shutdown, provided the device was not manually turned off.
Security experts note that the primary threat vector for digital wallets is social engineering rather than platform vulnerabilities. Users are advised to prioritise credit cards over debit cards within mobile wallets to prevent immediate access to personal funds in the event of fraud. While losing a phone allows for remote disabling of card access via online portals, the inability to pay without power or acceptance at all terminals means digital wallets should complement, rather than replace, traditional payment methods.