Morgan Stanley demands Tesla prove Robotaxi and Optimus viability
Rising costs and negative free cash flow prompt Wall Street’s most prominent bull to insist on measurable progress in autonomous vehicle and robotics divisions before justifying higher valuations.
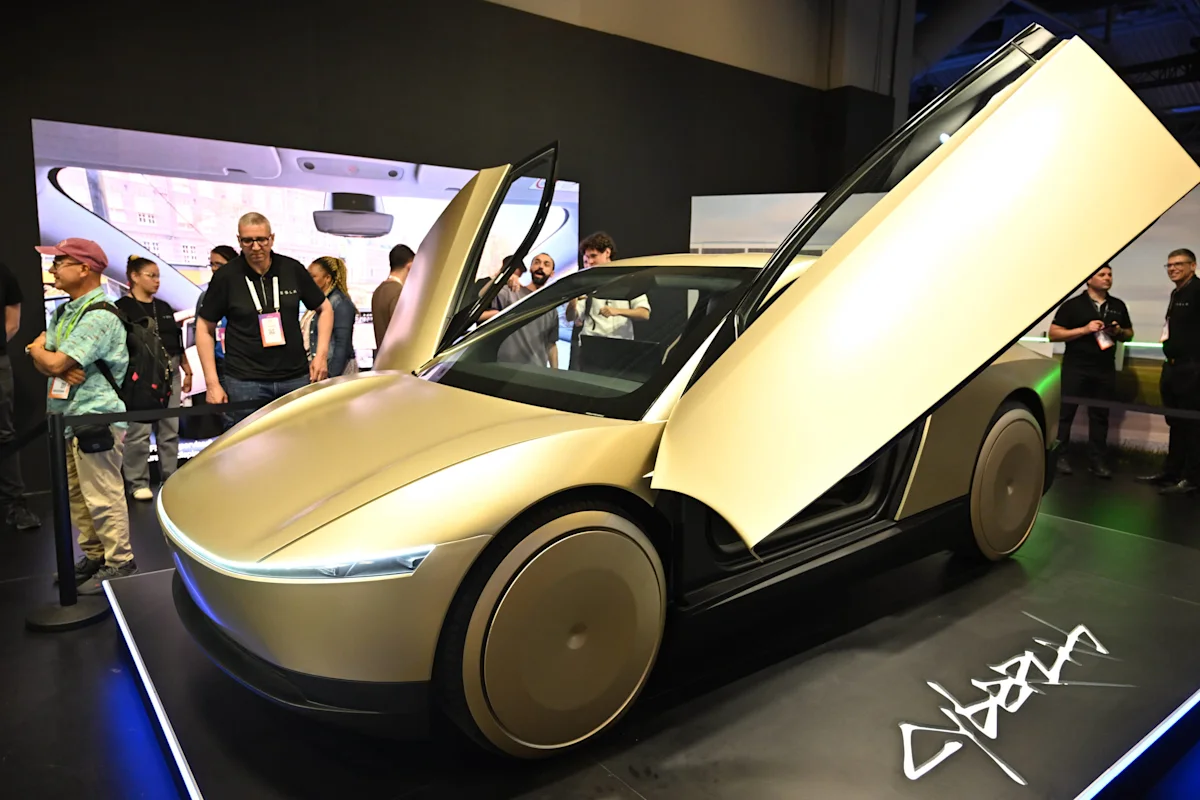
Morgan Stanley analyst Andrew Percoco has issued a direct assessment of Tesla, maintaining an Equal Weight rating and a $415 price target while emphasising that the company must demonstrate tangible progress in its artificial intelligence initiatives. Issued on 11 August, the note acknowledges that Tesla’s long-term thesis as a leader in physical AI remains intact, but argues that current financial metrics require immediate improvement to support higher valuations.
Percoco, who assumed Tesla coverage from Adam Jonas after Jonas moved to the automotive sector, highlighted a divergence between Tesla’s strategic potential and its current financial reality. The analyst pointed to rising research and development spending, declining gross margins, and negative free cash flow as key concerns. These factors have sharpened the focus on measurable outcomes, particularly regarding the Robotaxi and Optimus projects, which Percoco noted are currently insufficient to justify premium pricing.
While Tesla’s Full Self-Driving (FSD) adoption reached a 55% attach rate on North American deliveries—surpassing Morgan Stanley’s modelled estimate of 25% to 30%—this data point alone does not satisfy the analyst’s criteria for a buy rating. Percoco stressed that investors require clearer evidence of Robotaxi scaling, specifically looking for higher vehicle utilisation, increased revenue per vehicle, and robust safety standards that do not rely on heavy remote support or expensive hardware upgrades.
Morgan Stanley forecasts Tesla’s Robotaxi fleet to reach 1,500 vehicles by the end of 2026, with a ramp to 30,000 units by 2030. However, Percoco indicated that fleet size is less critical than fleet productivity at this stage. The analyst noted that recent disclosures regarding expansion into cities such as Austin, Dallas, Houston, and Miami were viewed as helpful but inadequate without data on ride volume and operating costs relative to customer payments.
Regarding the Optimus humanoid robot, Percoco stated he is seeking evidence of commercial viability beyond start-of-production announcements. Investors are looking for manufacturing cost estimates, external customer orders, and demonstrations of operation without constant human supervision. Tesla has confirmed Optimus is working within its own factories, but the market requires proof of commercial contracts and public demonstrations in uncontrolled settings before assigning value to the division.
Tesla shares were trading around $330 at the time of publication, implying approximately 26% upside to the $415 target. Percoco clarified that the Equal Weight rating is not a bearish call, but rather a reflection of the risk-reward dynamic. The analyst’s note serves as a checklist for the company, indicating that while the AI strategy is not in question, the timeline between capital expenditure and visible business results must accelerate to satisfy institutional investors.


