Drake’s US Property Gift Triggers $538,000 Tax Liability for Canadian Rapper
While the recipient faces no immediate income tax, the Canadian domiciled giver confronts a steep federal gift tax bill due to the absence of a lifetime exemption for non-residents.
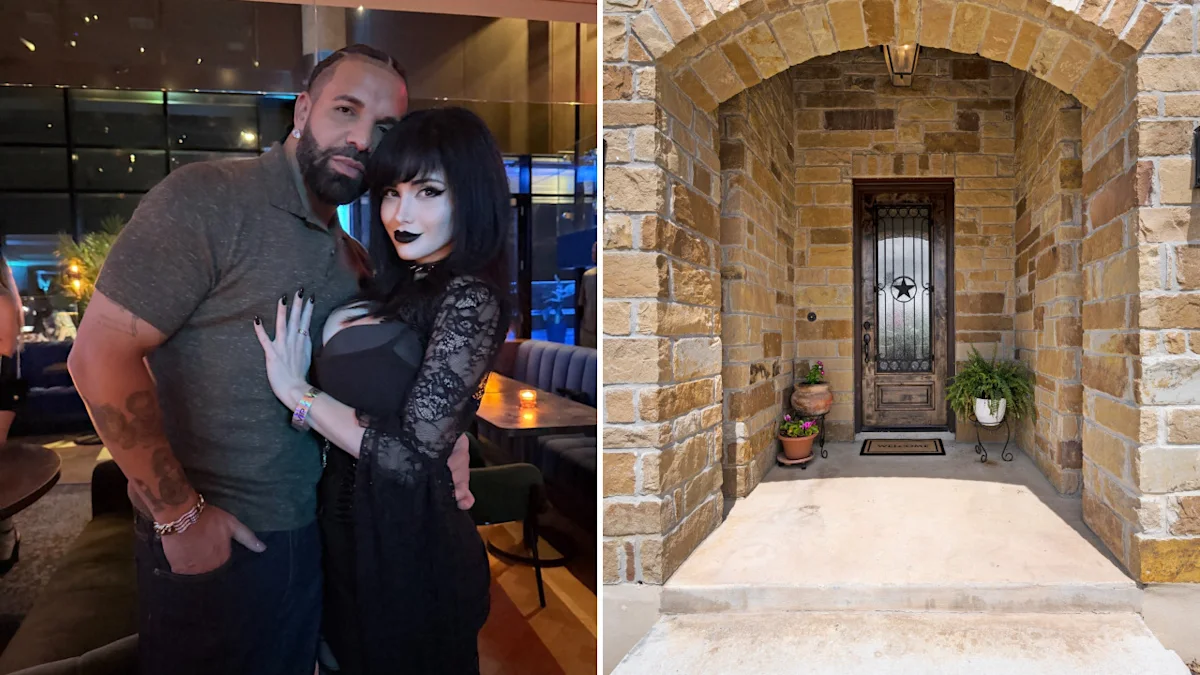
Canadian rapper Drake has confirmed a commitment to purchase a residence for the mother of 23-year-old streamer Pinkchyu, also known as Lin Lamar, following her selection on a Kick speed-dating broadcast. The offer was made on 8 August during a stream hosted by Stake to mark its ninth anniversary, where Drake chose Lamar from a field of 20 women. Lamar confirmed to TMZ that the transaction is proceeding, with her responsible for selecting a property listing for Drake to fund.
The financial mechanics of the transfer hinge on whether the IRS classifies the house as a taxable prize or a non-taxable gift. Under the precedent set by the 1960 Supreme Court case Duberstein, a transfer is considered a gift only if driven by detached generosity rather than obligation or promotional expectation. Given the structured nature of the dating show, which featured tiered prizes including cash and luxury items, the transaction risks being viewed as a prize, which would subject the recipient to ordinary income tax of up to 37 per cent on the property’s market value.
If classified as a gift, the tax burden shifts to the giver, but Drake’s Canadian domicile creates a complex liability profile. While US citizens benefit from a $15 million lifetime gift and estate tax exemption, non-US domiciled individuals are excluded from this benefit. Consequently, Drake faces a potential federal gift tax bill of approximately $538,000 on a hypothetical $1.5 million property, calculated after applying the $19,000 annual exclusion but lacking the lifetime shield available to domestic donors.
The absence of a gift tax treaty between the United States and Canada exacerbates the cross-border friction. For the recipient, the primary compliance requirement involves filing Form 3520 to report the receipt of more than $100,000 from a non-resident alien. While no tax is owed on the form itself, failure to file incurs a penalty of five per cent of the gift’s value per month, potentially reaching $375,000 for a high-value property.
Ongoing costs in Texas, where the property is likely located, present a separate financial challenge for the recipient. Texas relies heavily on property levies, with an average effective rate of 1.40 per cent, and insurance premiums have surged by 60 per cent between 2019 and 2024. Although a homestead exemption increase approved in November 2025 provides relief for the 2026 tax year, the structural costs of ownership remain substantial for a high-value asset.